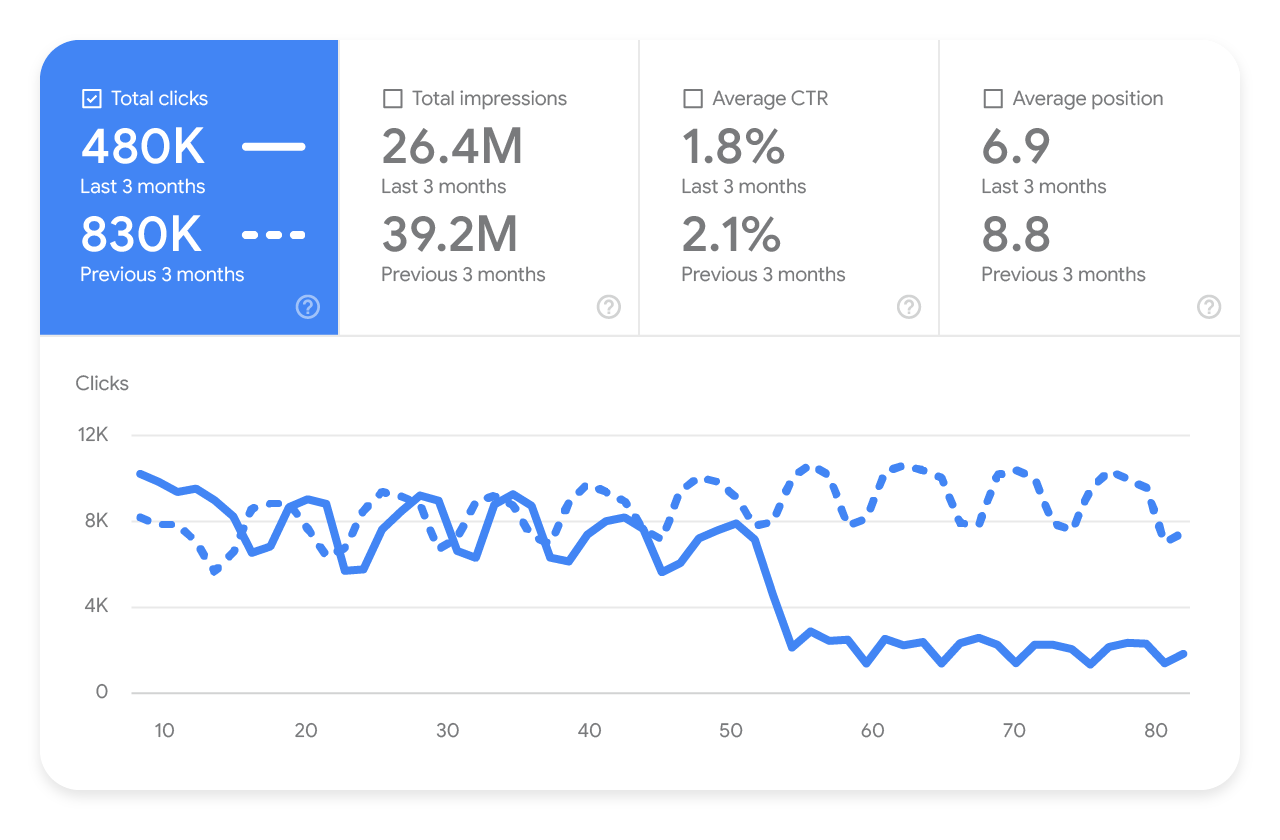
Google’s published Search Console sample compares the last three months with the previous three: clicks fall from 830K to 480K while average position improves from 8.8 to 6.9. Compare matched queries, service pages and date periods before changing a CPA page. These search metrics do not establish suitable inquiries or consultations.[5]
Local marketing improves when accurate public information, useful service explanations, prospect trust, intake response, and suitable engagement outcomes are reviewed together. More impressions do not help if pages attract services the firm does not offer, location claims are weak, forms request unsafe details, or reports stop at clicks.
Do not optimize through city-name repetition, manufactured reviews, misleading specialties, unsupported results, hidden disclosures, or pages for offices and services that do not exist. Preserve company ownership and measurement history before changing domains, URLs, profiles, tags, or phone numbers.
How to choose the right CPA and financial firm marketing improvements
A useful optimization program increases qualified visibility for approved services and real locations, improves page and profile accuracy, reduces irrelevant paid demand, shortens response, protects prospect information, and connects marketing effort to consultations, proposals, and accepted engagements.
- Pages appear for services, locations, or client types the firm does not support.
- Titles and ads promise expertise, results, fees, or credentials that the page and approval record do not support.
- Several city pages repeat the same text without useful local or service information.
- Business Profile calls, forms, and Ads conversions are counted without service fit, consultation, proposal, or engagement status.
- Prospects wait too long or submit sensitive financial details through a general form or email reply.
- Content is rewritten for rankings without a user task, professional review, current source, internal link, or outcome measure.
Find qualified local demand and trust gaps
Relevant impressions with weak clicks
Diagnosis: Use Search Console by query and page, then inspect title, description, position, device, service fit, location, visible answer, competing result type, and actual inquiries. Do not assume every impression deserves a click.
Search Console measures search visibility and clicks; it does not establish consultation or engagement outcomes. [1]
CPA and Financial Firms Marketing improvement: Improve the page’s useful answer, state the approved service and realistic geography clearly, strengthen internal context, and revise the result text without unsupported claims or repetitive city stuffing.
Measurement: Track qualified query clicks, click-through rate within comparable positions, valid inquiries, consultations, and accepted engagements for the same page group.
Thin or duplicate service and location pages
Diagnosis: Compare pages for unique service scope, audience, process, preparation, records, responsible professionals, office or service-area facts, internal links, qualified demand, and accepted outcomes. Identify interchangeable text and unsupported locations.
CPA and Financial Firms Marketing improvement: Consolidate overlap or rebuild a page around a distinct user need and true location relationship. Explain how Lawrenceville, Suwanee, Gwinnett, Atlanta, or Georgia clients are served only when it is accurate and useful.
Measurement: Track duplicate-page switching, qualified local clicks, accepted inquiries by location, engagement outcomes, and pages retired or strengthened responsibly.
Google Business Profile inconsistency
Diagnosis: Review ownership, categories, eligibility, address or service area, hours, phone, website, services, photos, questions, reviews, edits, duplicates, and public consistency. Test the linked page and phone route.
CPA and Financial Firms Marketing improvement: Correct inaccurate information, resolve improper duplicates through supported processes, assign backup ownership and review response, document changes, and monitor rejected edits and suspension warnings.
Apply Google’s actual business and practitioner eligibility rules and represent the real operation accurately. [2]
Measurement: Track profile actions, connected calls, valid inquiries, edit rejections, duplicate resolution, ownership tests, and public information accuracy.
Improve pages, profiles, campaigns, calls, and forms
Professional claims lack current support
Diagnosis: Inventory credentials, designations, memberships, specialties, comparisons, results, testimonials, awards, rankings, fee statements, office claims, and paid content. Locate support, approval, date, and disclosure decision.
CPA and Financial Firms Marketing improvement: Obtain accountable review, correct or remove unsupported wording, add approved disclosures, verify organization-logo use, and schedule rechecks after service, credential, rule, fee, or personnel changes.
Measurement: Track reviewed assets, unsupported claims removed, expired support, approval time, corrections, and recurring claim categories.
Paid search attracts unsuitable inquiries
Diagnosis: Review search terms, locations, schedules, devices, ads, pages, calls, forms, service fit, consultation, proposal, and accepted outcomes. Separate research, jobs, support, unsupported work, existing clients, and out-of-area demand.
CPA and Financial Firms Marketing improvement: Add precise negatives, tighten approved service themes and geography, align ads and pages, run during intake coverage, improve routing, and optimize toward suitable consultations and engagements rather than every contact.
Measurement: Track irrelevant spend, cost per suitable consultation, proposal and engagement rate, response time, and spend by accepted service and location.
Forms collect unsafe or unnecessary detail
Diagnosis: Review fields, free text, file upload, URLs, analytics parameters, notifications, access, retention, mobile use, warnings, and secure follow-up. Test exactly what reaches Google and outside providers.
CPA and Financial Firms Marketing improvement: Collect only routing information, remove sensitive values from analytics, send financial records to an approved portal, secure the destination, clarify the next step, restrict access, and define retention.
Google’s ordinary Analytics collection must exclude personally identifiable information; inspect actual URLs and event data. [3]
Measurement: Track form completion, unsafe-data findings, secure follow-up completion, routing accuracy, spam, unauthorized access, and valid inquiries.
Calls are measured without useful outcomes
Diagnosis: Compare phone clicks, connected calls, missed calls, duration, after-hours routing, recordings where used, existing clients, service fit, consultations, proposals, and accepted engagements. Identify provider-owned numbers.
CPA and Financial Firms Marketing improvement: Keep numbers under firm control, improve routing and coverage, define useful call outcomes, document recording and retention decisions, and connect approved status back to reporting.
Measurement: Track connected and suitable calls, missed calls, response time, consultations, proposals, accepted engagements, and number-ownership tests.
Connect analytics to response and accepted engagements
Slow or inconsistent lead response
Diagnosis: Measure first useful response by source, service, location, day, time, owner, and capacity. Review failed notifications, duplicate follow-up, unanswered voicemail, unsafe email requests, scheduling, and leave coverage.
CPA and Financial Firms Marketing improvement: Set accountable routing and response expectations, create backup coverage, standardize status and notes, move sensitive follow-up to approved systems, and review losses caused by delay or poor qualification.
Measurement: Track response time, contact rate, suitable consultation scheduling, proposal rate, accepted engagements, and qualified prospects lost to delay.
Reporting stops at clicks and leads
Diagnosis: Map source, service, location, valid inquiry, suitability, consultation, proposal, engagement, decline reason, and approved value category. Identify platform conversions that cannot be reconciled with intake.
CPA and Financial Firms Marketing improvement: Use non-sensitive identifiers and outcome categories, repair event and status gaps, reconcile systems, and report accepted engagements and capacity alongside traffic and lead volume.
Google distinguishes initial inquiries from qualified and converted lead stages. Any advertising upload requires a separate approved data/consent and implementation decision. [4]
Measurement: Track source reconciliation, suitable consultation rate, proposal rate, accepted engagement rate, cost per engagement, unknown source, and duplicate conversions.
Content and profiles lack maintenance ownership
Diagnosis: Find assets without a responsible professional, source record, claim support, last review, next review, change history, search or intake purpose, and accountable platform owner. Identify stale people, services, hours, locations, and links.
CPA and Financial Firms Marketing improvement: Assign professional and editorial owners, classify review frequency, update useful sections, archive versions, repair internal links, correct profiles, and retire material only after user and search effects are understood.
Measurement: Track on-time reviews, stale facts corrected, broken paths repaired, profile accuracy, qualified demand after updates, and responsible consolidation.
Measure useful visibility and maintain accurate assets
Review optimization with the professionals who approve public claims and the people who answer inquiries. Each monthly decision should identify the user need, service, location, evidence, privacy boundary, expected outcome, owner, due date, and later result.
- Qualified local visibility: Clicks and profile actions for approved services and real locations, separated from unsupported work, jobs, research, and existing-client demand.
- Public claim coverage: Material pages, ads, profiles, testimonials, fee statements, and credentials with current support, accountable approval, and version history.
- Inquiry response: Connected-call rate, form routing, time to first useful response, follow-up completion, and secure intake transition.
- Suitable consultation: Valid inquiries that match the firm’s service and location criteria and reach a scheduled and held consultation.
- Accepted engagement attribution: Approved non-sensitive linkage from source and service interest through proposal and accepted engagement outcome.
- Public information accuracy: Website, Business Profile, directories, phone, hours, credentials, services, locations, and professional information matching current operations.
Read CPA marketing results without confusing demand and delivery
Hypothetical reporting examples. Replace the labels with the firm’s approved intake stages; no sample represents an ALLMSP client result.
On a narrow screen, scroll horizontally to read every table column.
| Result observed | What it does and does not establish | Next check |
|---|---|---|
| Relevant page impressions increase | The page appeared more often; no new engagement is established. | Compare matching query/page clicks and suitable inquiries. |
| Consultation form succeeds | A request reached the intake system; service fit and engagement are still unknown. | Verify routing and record a non-sensitive suitability/status decision. |
| Accepted engagements are flat despite more inquiries | The extra demand may be unsuitable, slow to reach staff or beyond capacity. | Review decline reasons and response delay before raising the budget. |
Frequently Asked Questions
How can CPA firms improve relevant Search Console impressions that do not earn clicks?
Check service fit before changing the title. Filter Search Console to the same page, query theme and device, then compare similar periods and positions. Improve the page’s direct answer, preparation information and accurate service/location wording where relevant demand exists. A click-through-rate change caused by position or unrelated queries is not a reason to add stronger credential or results claims.
Supporting sources: [1]
Should an accounting firm create a separate page for every nearby city?
No. Create a separate page only for a distinct service or truthful location need that deserves its own useful answer. Explain who the service suits, how work is delivered and what a prospect should prepare. A city name alone does not justify a page or prove an office exists. Consolidate overlapping pages carefully, with redirects and internal-link checks where needed.
What should a CPA firm optimize in Google Business Profile?
Verify eligibility, ownership, real-world name, core category, accurate location or service area, hours, phone and linked page. Review individual-practitioner conditions before adding a separate professional listing. Correct duplicates through supported Google processes instead of multiplying profiles. Test the telephone and contact route; an accurate listing is less useful when it sends prospects to an unattended channel.
Supporting sources: [2]
How should CPA firms improve testimonials and professional claims?
Keep evidence for credentials, awards, testimonials, specialties, fees and stated outcomes, with the approving professional and review date. Correct expired or ambiguous statements wherever they appear, including ads and directories. Do not imply a designation, regulatory registration or result the firm cannot substantiate. The responsible reviewer should determine applicable professional and advertising rules for the firm’s actual services.
How can accounting firms reduce irrelevant Google Ads inquiries?
Classify actual search terms and inquiries by accepted service, geography, client type and outcome. Exclude clearly irrelevant demand and align ads with the correct service page and available intake coverage. Keep initial contacts distinct from suitable consultations and engagements. Before sending later-stage feedback to Ads, review eligibility, consent and the data fields; financial records do not belong in campaign exports.
Supporting sources: [4]
How can a CPA firm improve contact forms without collecting sensitive data?
Use the public form to request the service category and minimum contact/routing information. Direct tax returns, account details and financial records into the firm’s approved secure intake. Submit dummy data to inspect URLs, page titles, events and notification destinations. Prevent sensitive values from reaching ordinary Analytics collection rather than relying only on best-effort redaction.
Supporting sources: [3]
Which calls should a CPA firm count as marketing conversions?
Track a telephone click, connected call and suitable inquiry as different events. Reconcile a sample with the intake outcome so existing-client support, spam and wrong-service calls do not look like new opportunities. Use an agreed consultation or engagement stage for business reporting. Keep call-recording, retention and consent decisions in the firm’s approved process.
How quickly should CPA and financial firms respond to new inquiries?
Choose a first-useful-response target the staffed team can meet and publish accurate channel hours. Assign backup coverage and an escalation path for unclaimed inquiries. Measure the time until someone gives a relevant next step, rather than counting an automated acknowledgment as a completed response. Review delays by service and day so capacity problems are visible before increasing campaign volume.
How can a CPA firm measure marketing through accepted engagements?
Use an approved non-sensitive reference to reconcile inquiry source, suitability, consultation, proposal and accepted engagement in restricted reporting. Keep duplicates, unknown sources and declined work visible. Compare cost and available service capacity with accepted outcomes, not only form totals. Uploading any outcome to an advertising platform needs a separate approved implementation and privacy review.
How should CPA firms maintain marketing content over time?
Assign a professional reviewer and editorial owner to each important page and profile. Recheck after a service, credential, fee, office, staff or rule change; set a risk-based regular review for the rest. Keep the prior approved version and test the contact and internal-link paths. Retire or merge a page only after understanding its useful content and existing traffic.
Choose the next step
- Audit Financial Marketing Accounts, Claims, and Conversion Tracking — Audit accounts and event integrity before acting on doubtful marketing totals.
- Build Measurable Marketing for Accounting and Advisory Services — Define qualified inquiry and engagement stages before optimizing the campaigns.
Sources
- Search Console: Performance report overview and basic setup. Clicks/impressions/CTR/position with query/page/device/date filters describe search performance, not consultations or signed clients. ↩
- Google Business Profile: Guidelines for representing your business. Accurate real-world location/name/categories, office eligibility, practitioner specifics and business-controlled telephone; service-city pages do not create eligible offices. ↩
- Google Analytics: Best practices to avoid sending personally identifiable information. Avoid PII in ordinary Analytics collection including URLs, page titles and event data; redaction is not a replacement for preventing collection. ↩
- Google Ads: About qualified leads and converted leads. Qualified and converted lead milestones can represent defined later lead stages; privacy/consent/implementation eligibility must be checked separately before any upload. ↩
- Google Search Central: Debugging drops in search traffic ↩